Showing posts with label aid. Show all posts

Chimera's’ currency debate


“Chimera” is the term coined by Niall Ferguson to represent the heavenly marriage between China and America that between 1998 and 2007 accounted for about 40% of global growth (Ferguson, 2008). As put by the Harvard Professor, in this marriage “the Chinese did the saving, the Americans the spending. The Chinese did the exporting, the Americans the importing. The Chinese did the lending, the Americans the borrowing”

Yet, today, with the US economy scrambling to find a way to a sustainable recovery after the financial disaster of the 2007-8, many are asking China to re-balance its economy; definitely an indication that this marriage might be finally on the rocks.
That the economies of the US and China have become so intertwined is certainly a sign that times have changed; after years of isolation, the Communist China slowly started to integrate in the world economy, quickly flooding the world with its cheap exports while the Americans, leaving aside years of misunderstandings, soon took advantage of this situation and started to buy cheap Chinese goods, while US companies did not hesitate to outsource their operations in the favourably enterprise zone set up by the Chinese government. Indeed, to date, US are the second-biggest Chinese trade partner and China is the biggest exporter in the world.

Without doubt, China’s rise has been the most successful development story of the past twenty years. It has embraced Capitalism while still preserving an authoritarian government structure of one-party state; it has opened its economy and attracted large flows of Foreign Direct Investments (FDI). From a country on the brink of a famine due to its disastrous central planning system, today China enjoys higher standard of living, to an extent that the number of people living in poverty have decreased to 8% in 2001 from 53% in 1991 (World Bank, 2010).
Nevertheless, the core of Chinese development has been an export–led growth strategy, a policy that has surely taken advantage of its abundant labour force (roughly 20% of world population) and relatively high human capital (typical of former Communist countries), an established, albeit not yet productive Industrial sector and the creation of special economic zones (SEZs) such as the ones in Shenzhen and in Guangdong.

The massive structural change that China undertook helped sustain the miraculous growth that followed the liberalisation of its economy. However, in order to make its exports even more competitive, the Chinese government had to embark on what has become an important milestone in its economic policy, that is the successful devaluation and unification of currency rates at the beginning of 1994 and the eventual peg of the Yuan (renminbi) to the US dollar (Naughton, 1996). 
China’s economic arguments for maintaining its currency pegged to the dollar have revolved around the need to maintain and increase the competitiveness of its exports as compared to competing countries. The mechanism (in general terms) is based on the fact that as the renminbi depreciated (hence the price of the US dollar in Yuan increased), China’s US dollar earnings from exports increased and the dollars spent on imports decreased. By keeping the renminbi artificially low, China created a dollar surplus, which in turn meant that the government had to buy the excess dollars (Krugman, 2010). If analyzed in a supply-demand framework, China’s increased exports lead to a proportionate spike in demand for Yuan (as items produced in China would have to be purchased in the local currency). In this situation, in order to maintain the peg, the Chinese government had to increase the demand for other currencies by buying dollars, euro, etc, and thus increase the supply of Yuan, which eventually helped maintain the peg.
The crawling peg system adopted by China could be placed in-between managed floating and the adjustable peg system (Sloman, 2006: 676). Thus the Chinese government adjusts the peg frequently by small amounts as the equilibrium exchange rate changes (ibid). In the short-term, therefore, the central bank of China had to intervene in the foreign exchange market in order to maintain the peg.

According to Fan Gang, a professor at the Chinese Academy of Social Sciences, the two main reasons why China decided to peg the renminbi to the US dollar were to maintain employment in export industries and to prevent its immature financial system from speculation that would occur if the Yuan was allowed to float freely (cited in Corden, 2009). Keeping the Yuan pegged to the dollar made Chinese exports cheaper, which is why China has been enjoying such a rapid export-led growth over the past decade. However, in order to maintain the exchange rate, the People’s Bank of China had to regularly purchase large amounts of dollars which led to more than 700 billion dollars  foreign exchange reserves by mid 2005 (Hill, 2009).
The People’s Bank of China has continued undertaking massive purchases of foreign currency ( to keep the exchange rate down, to an extent that in June 2009 it accumulated $2,132bn in foreign currency reserves, over 40 per cent of GDP (Wolf, 2009a). 


The fact that most of the foreign currency reserve (70%, ref) are in dollar-denominated securities, and a large proportion of these are in U.S. government bonds also had the unintended effect of helping finance the U.S. current-account deficit at very low interest rates. Still according to Ferguson (2008),"without those low long-term rates, it's hard to believe that the U.S. would have bubbled the way it did between 2002 and 2007".


Indeed, with the American shopping malls full of cheap goods made in China and the US consumer engaged in a buying spree thanks to a nearly costless borrowing financed by the same Chinese currency intervention, it is not coincidental that the US trade deficit with China reached worrying heights  of -268,039.8 in 2008 (US Census Bureau, 2010).
The record US trade deficit with China, as well as the claims that the Yuan was largely undervalued after so many years of rapid growth, were constantly putting pressure on China to let the Yuan float freely against the US dollar. Although since July 2005 China has introduced more flexibility in its exchange rate by linking it to a basket of currencies (the euro, yen and the US dollar), Morris and Lardy (2009) argue that the change to a crawling peg system has had very little effect in practice. 

China allowed the Yuan to rise by 21% against the dollar in the three years to July 2008 but since then it has more or less kept the rate fixed (ibid). 
In spite of calls for a stronger renminbi and threats of protectionist measures such as tariffs on Chinese steel pipes and tyres have started as early as 2005, the worst crisis since the 1929 crash has certainly exacerbated the unsustainability of the current imbalance. In fact, the current US administration in its stimulus bill passed in January 2009, with the inclusion of the controversial “Buy America” provision that bars foreign steel and iron from the infrastructure projects laid out by the $819 billion economic package (Faiola, 2009) has effectively tried to stimulate the domestic production in order to save jobs and help the heavy industry at the expense of otherwise cheap imports (a Trade diversion in practice).
Despite the relative success of these measures, the US trade deficit with China has slowly decreased - at December 2009 it was -226,826.1 (US Census Bureau, 2010). In order to re-balance the world economy it is required that the renminbi reflects its true value, hence an appreciation of the currency that mirrors the growing status of the Chinese economy.
On the other hand China has had a ‘good crisis’ (Wolf, 2009); the high Chinese saving rate helped finance a massive fiscal stimulus programme of 4 trillion Yuan or $586 billion (The Economist, 2009). It was targeted at increasing the very low household consumption, which in 2007 was just 35 per cent of GDP (Wolf, 2009a). As shown in the graphs below (ibid), the government recovery programme has certainly facilitated a surge in Chinese domestic demand and the shrinking of its current account.


China’s government apparatus is also aware that time has come for the Chinese to let loose the dormant spending power of a high-saving population and shift to a new economic model that abandons its reliance on investments and exports; as also said by the Prime Minister  Wen Jiabao “we should focus on restructuring the economy, and make greater effort to enhance the role of domestic demand, especially final consumption, in spurring growth” (cited in Wolf, 2009b).
Nevertheless, despite the fact that the huge trade surplus has almost halved, the nature of the stimulus focused on state-investment that will probably increase its current account surpluses once again in future (The Economist, 2009) and the government is still accumulating foreign currencies to keep the exchange rate pegged. It has been deaf to the international chorus of voices calling on China to allow the renminbi to appreciate; indeed, the Chinese intervention in the exchange rate market is looking every day as a disruptive manipulation of the global economy.

According to Wolf (2009a), China has lost its “liberty of insignificance”, or rather that its actions nowadays, have a huge impact on the rest of the world. It is argued that a stronger Yuan would help rebalance China’s economy towards domestic spending by increasing the purchasing power of Chinese consumers, as well as give China’s central bank more control over inflation by having more freedom in setting adequate interest rates (The Economist 2010b). Although such an appreciation could cause a wave of job-cuts in the export sector of the Chinese economy, the increased domestic purchasing power will contribute to a gradual restructuring towards services that tend to be rather labour-intensive and hence likely to mitigate the impact of this restructuring (The Economist, 2010c). Short-termism, protectionist and nationalist sentiment on behalf of China’s ruling elite that results in further postponing or even stubbornly refusing action is likely to make the avoidance of a trade war between the US and China, a trade war that is likely to result in not only a huge welfare loss for both countries but also in a suffocation of world-wide economic recovery. Ambition and pride, one would argue, have been both the blessing and the curse of great states – the question this time is whether the world is prepared to pay the price.
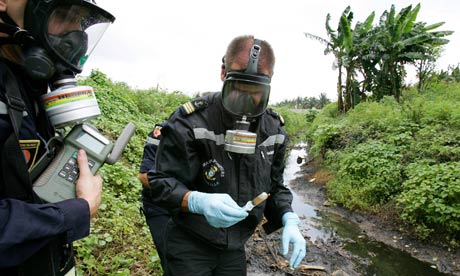


To what extent can the behaviour of Trafigura in the Ivory Coast be explained as acceptable business activity?


If we would like to answer to the question in consideration of what is generally accepted as ethical, the answer would be a categorical No; however the clamour generated, the legal implications and the fact itself that the episode has actually happened means that the answer is not so straightforward. It does deserve a much broader discussion.
The Trafigura case is particular because of the recent headlines that it has received all over the world, despite the facts date back to August 2006. The wide coverage of the incident given in the press and then amplified by the blogosphere has certainly contributed to a diffused revulsion of the public opinion towards the behaviour of the company; indeed, bumping toxic waste in a third world country with the potential environmental and human disaster surely hurts the sensibilities of many people.
If the act would have been the sole work of an individual, there is no doubt that he/she would be legally been held responsible for the damage; however the fact that we are discussing the activity of an organisation requires a different analysis. We may arrive to the same conclusions, though it is worth contextualising the fact to understand why this case may be different or to some extent be justified.
The UK legislation recognises the “duty of care” of an organisation, a proposition that implies accountability and therefore social responsibilities. Responsibilities are defined by laws; however in such case the law seems to have not been enough to bring a strong case against Trafigura, despite the objectionable events.
Indeed, according to Milton Friedman, an organisation’s responsibility does not go beyond the abiding to the rule of law; its social action, says the American economist, is realised in the mere creation of wealth.         
Nowadays, we are obviously not satisfied with the neo-classical assumption; however Milton’s view represents the basis of our socio-economic framework, profiting is not banned and Governments are in charge of the distribution of the social wealth. So, why do we need organisations to act ethically?

The answer may lies in the definition that we give to wealth. The rational approach indicates in the economic maximisation of the resources the road to the happiness, the individual thrives to do better and seeks perfection. However, no individual is perfect and as we have recently seen, the implications for irrational exuberance are shared by the society as whole. The individual may aspire to be better; indeed our society rewards a place in the history to people that have most contributed to the welfare of many, not certainly to themselves.
The forms of contribution are subjective. They can be economically rational, legal, democratic and reverential of the host-culture; however organisations as entities that reflects individuals actions, have to nevertheless act in respect of the principle of inviolability of the human being, always and everywhere. A test that Trafigura has blatantly failed.
The actions of Trafigura in Ivory Coast are the consequences of specific decisions made by individuals that are part of our society, hence people that refer to a general accepted morality code. However, what has probably played a big role in this decision making process is the culture of the organisation and to some extent of the industry. 
    
Trafigura is an Anglo-Dutch commodity trading company that aims, according to his mission statement, to be a major player in the market by spotting opportunities and profiting from the volatility of the commodities’ prices. It is not a listed public company, though it still operates in a legal framework and it is committed to the interests of its owners, investors and employees. Moreover, it is also involved in charity works through its Trafigura Foundation.
The financial industry has certainly contributed to the global growth of the past twenty years, though the recent events have highlighted that very often the motivation behind the industry performances was the size of bonuses. The industry is frequently characterised as very masculine, hence rational, calculating, where power and politics are big determinants.
If we consider Trafigura behaviour within this context, we should accept the relational view of power or rather the fourth dimension of power theorised by Foucault and critically developed in Linstead et al (2009).
According to this perspective power is not seen as held by individuals but rather it is implicitly accepted as the normal state of the things. Hence, specific practices, techniques and procedure are developed in attempts to shape the conduct of the others (Linstead, 2009 p.281) that unconsciously understand them as the constructed reality.
Indeed, if we look at the emails that the Trafigura people were sending each other during the negotiations to get rid of the toxic waste, we fail to individuate a person or a group that force the hand. Instead we assist to a shared removal of any potential regret for the known consequences of their actions, as this is the way things are and they were acting consequently.
In fact, for the Probo-Koala incident, the company has defended itself vigorously denying that the environmental damage on the coast of Abidjan has been caused by its activities, despite an UN report says otherwise.
Another important factor that the Trafigura case has highlighted is the globalisation of the response to the company’s behaviour. In fact, in finding a place where to bump the caustic soda, Trafigura has consulted different government and agencies, each ones holding different rules.
The fact that the company has not been able to discard of the toxic waste in Netherlands is the consequence of the Dutch law conforming to an ethical value of not harming their people and their environment. Indeed, the company finally found in an Ivorian contractor a person able to discard the waste without causing too much noise; that is not to say that Ivory Coast’s laws are not ethical but surely in a semi-dictatorial country very often the ethical values corresponds to the personal interests of few.

The fact that organisations may encounter different ethical standards and the fact itself that organisation are influenced by an own national culture has been theorised by G. Hofstede. According to his perspective, national cultures are dominant in an organisation; hence the organisation culture reflects the shared values and practices of a particular nation or region.
There is no doubt that Trafigura behaviour reflects an indiscriminate form of Capitalism typical of Anglo-Saxon socio-economic models; however it still represents an abjuration of the shared ethical values of the culture that it stands for.
Indeed, the massive reaction of the social-community to the episode has signified that the defence of the inviolability of the human rights is not circumvented to national boundaries but it is instead projected wherever any abuse may happen, regardless of the legal framework in which it takes place. Globalisation has enlarged the stake holding to which an organisation responds.
As a man of faith I wish the world were otherwise, Mr. Obama said, but as president I must treat it as it is.

Does Aid Work?


Today we are going the review the article "Does aid work?" published in the 1989 in the book "Leading Issues in Economic Development".
The article aims to evaluate the effectiveness of foreign aid as a tool for stimulating economic and social development in LDCs countries.

Since the article has been published in the 1989, we are first going to review the article in  the light of its findings, then on the basis of its conclusion we are going to see the eventual progress that have been made in the suggested direction.

Foreign Aid as highlighted in the article has been intense scrutiny from both the sides of the political arena for the failure to show solid improvements in the recipient's economies 

The right wings, in fact, see aid as the umpteen proof that government intervention does not work, indeed it only produce a welfare mentality and in most case filling the pockets of corrupt bureaucrats    
On the other hand, the critics of the left even argue that foreign aid can be a force of anti-development, widening the gap between the rich and poor, perpetuates dependency, and increase the influence of the donor over recipient

Regardless of the ideology a first assessment is presented by the 

According to the former director of OECD DEVELOPMENT ADVISORY COMMITTEE 
  • record is mixed
  • achievements , where aid has acted as catalyst (eg South Asia, agriculture programme with a very thin spread of aid per capita and Taiwan , S.korea with massive aid 
  • high correlation with decline in birthrates
  • very importantly without aid the growth registered in the '60 and '70 would have been slower

The rationale behind the use of foreign aid to promote economic growth can be traced in the Harrod-Domar model, a model that promised poor countries growth right away through aid-financed investment.

According to the theory there is a direct relationship between a country's rate of net saving and its rate of output growth 
hence g= s/K where K is the national capital output ratio (Y/k)

If a rate of growth is targeted at 5% and K is 3, it is required a net saving rate of 15%, therefore if a country can only produce an annual rate of net saving rate of 10%, it is said that 5% saving gap exist
Therefore donors fill the financial gap with foreign aid to attain target growth.

However the main criticism from both the parties regards whether substitute for domestic saving and not complementing it

According to the critics the domestic rate of saving is less than it would be without foreign aid investment is lower than it would be without aid

Regarding the first contention 
Most of  studies suggest a positive marginal propensity to save while in the worst case scenario a study cited in the article found that only 23% of foreign capital inflows were offset by a decline in domestic saving
It is difficult to stimulate the desired level of domestic savings
- Meeting a savings gap by borrowing from overseas causes debt repayment problems later, so there is only a short-term gain 
- Diminishing marginal returns to capital equipment exist so each successive unit of investment is less productive and the capital to output ratio rises.

The second  is not empirically testable, although we may expect that because in many case the dividend of the induced economic growth are not reinvested because of the string attached to the aid and in the case of FDI,  very often there is evidence of crowning out local investment , hence the real gain in investment level in the best case is minimal 
although in Asia there is evidence that govt selection of FDI did stimulate crowding in of domestic investment 

Conclusions 
with experience failures have diminished
more effective collaborations between recipient and donors
end of cold war has reduced the need the politicisation of aid